Saturday, September 2, 2017

Krugman on housing

I to a greater extent than ofttimes than non don't read Paul Krugman -- bad for the blood pull per unit of measurement area -- as well as I fifty-fifty less ofttimes respond -- don't dignify the insults or feed the trolls. But I took a long plane flying yesterday , as well as the Times was all I had to read , as well as hence I stumbled across his column on housing.

After getting through the customary political barbs at Republicans (Rick Perry inwards this case) , as well as snarky insults ("the habit economists pushing this trace accept of getting their facts wrong") , I constitute something almost sensible.

People , particularly "middle class" people ,  are moving away from New York as well as to California , as well as to Texas as well as Georgia. Nominal payoff inwards Texas as well as Georgia are non higher. So why exercise they move? Answer: Real wages are a lot higher , because the cost of living is as well as hence much less. It's practically similar moving to a unusual province (in  many ways!). You are earning $100 ,000 inwards the un-hip business office of Brooklyn , they offering you lot lxxx ,000 zingbats to motion to Truckgunistan. Is it a proficient deal? Well , you lot larn ii dollars per zingbat , as well as hence sure!

Real payoff are higher inwards large business office because housing costs are lower. And housing costs are lower because...
high housing prices inwards slow-growing states also owe a lot to policies that sharply bound construction. Limits on edifice summit inwards the cities , zoning that blocks denser evolution inwards the suburbs as well as other policies constrict housing on both coasts; meanwhile , looser rule inwards the South has kept the furnish of housing elastic as well as the cost of living low.
So conservative complaints nearly excess rule as well as intrusive authorities aren’t exclusively incorrect ,
Yup. When people desire to alive somewhere , you lot tin build denser as well as higher -- the best response -- you lot tin build out -- causing a lot of transportation gridlock , long commutes , as well as pollution equally people drive past times artificially depression density housing on their vogue to run -- or you lot tin lookout adult man prices explode.

There is enough to a greater extent than incorrect inwards the economic science of the column -- for instance , "workers" aren't a homogenous lot , as well as "productivity" is non a constant of nature , independent of numbers or of occupation. Hedge fund managers are productive (at to the lowest degree past times green measurement) inwards New York. That does non hateful that machine assembly workers volition live to a greater extent than productive if they motion dorsum to New York. So moving everyone dorsum to New York as well as California is non probable to double GDP. But it's overnice to come across an admission of a major work caused past times regulation.

On the second-to-last judgement , he's even as well as hence going strong
It would live cracking to come across the existent telephone substitution — affordable housing — larn out a national issue. 
Indeed it would. But faced alongside the inevitable , unavoidable , logically unassailable decision -- nosotros need a massive liberalization of zoning laws , planning restrictions , as well as and hence forth , allowing people to build upwardly as well as dense , as well as thereby exercise an immense furnish of slightly used housing likewise equally people motion out into the novel stuff--his political blinders but won't allow him exercise it:
But I don’t recall Democrats are willing to nominate Mayor Bill de Blasio for president but yet. 
Bill de Blasio?? That champion of gratuitous markets?  From that paragon of low-cost housing ,.... New York City? Touting that well-proven , time-tested solution: to a greater extent than rule , set-asides , rent command , authorities structure , as well as quotas? Just similar they accept inwards Texas as well as Georgia?

Well , today Grumpy got ii proficient LOLs from the news.

Liquidity in addition to IOR

Re: the large residue canvas together with how it improves fiscal stability.

Rodney Garratt , Antoine Martin , together with James McAndrews at the New York Fed bring a really dainty post , Turnover inwards Fedwire Funds Has Dropped Considerably since the Crisis , but It’s Okay.

Before the crisis , banks held most $50 billion of reserves at the Fed. That's non a lot of money. When banks desire to pay each other -- state yous write a banking concern check to me , hence my banking concern has to larn coin from your banking concern -- they exercise it past times transferring reserves through the Fedwire.  So , that's why banks maintain some reserves there.

But $50 billion is tiny compared to $10 trillion of M2 , together with banks purpose reserves to clear fiscal transactions too. Influenza A virus subtype H5N1 huge amount must menstruum past times passing around these tiny reserves. How did banks exercise it? What happens if banking concern B says to banking concern Influenza A virus subtype H5N1 , "send us $10 million" together with banking concern Influenza A virus subtype H5N1 didn't bring $10 i G 1000 left at that 2d inwards reserves?

Answer: "intraday overdrafts." The Fed would lend banking concern Influenza A virus subtype H5N1 the $10 i G 1000 -- merely flip a switch together with seat $10 i G 1000 inwards their reserve concern human relationship , together with telephone band the loan an property corresponding to this liability. Influenza A virus subtype H5N1 hence pays B , together with works difficult to brand certain that it collects $10 i G 1000 from C together with D past times the destination of the day.

Source: Rodney Garratt , Antoine Martin , together with James McAndrews at the New York Federal Reserve


As yous tin encounter , such "overdrafts" accounted for 50-60 per centum of all Fedwire transactions before the vast increment inwards reserves.

It's a organisation that makes a lot of feel , hence long equally banks never neglect together with don't abuse it. It allows the organisation to gain a much higher book of transactions alongside less non-interest-bearing assets. Instead of cash inwards advance for every buy , settling upwards i time per 24-hour interval way yous exclusively ask to encompass the worst possible daily total menstruum , non the worst possible intraday menstruum , similar if $10 i G 1000 goes out 10 minutes before some other $10 i G 1000 comes in.

But straightaway , banks bring $4 trillion of reserves. They're sitting around equally investments , really. As long equally they pay total marketplace position involvement , at that topographic point is no argue for banks to become to all this essay to larn past times alongside piddling reserves. And nosotros seen inwards the graph precisely what you'd expect. If banking concern Influenza A virus subtype H5N1 owes banking concern B $10 i G 1000 , it merely sends the $10 i G 1000 , no ask to borrow it for 10 minutes from the Fed.

The article explains all this well. Influenza A virus subtype H5N1 few quibbles
The shift inwards funding away from overdrafts together with toward concern human relationship balances has significantly increased the amount of liquidity needed to fund payments inwards Fedwire Funds. 
I yell upwards reality is the other way. The vast amount of liquidity banks bring chosen , together with volition overstep on to remove hence long equally reserves pay marketplace position interests , hateful they bring abundant liquidity to fund payments straight on Fedwire. It is non "needed." (Mistaking "choice" for "need" is a favorite Econ 101 fallacy.) The infinitesimal the Fed tries to pay less on reserves than brusque term T bills pay , banks volition remove to become dorsum to the quondam system.

And turnover -- which they signal out has plummeted equally inwards the graph below (ignore the "counterfactual") -- is a totally misleading statistic. Turnover is transactions / reserves. Transactions haven't fallen , reserves bring exploded. I presume a graph of the total unwrap of transactions shows piddling modify , or at to the lowest degree no such cliff.

Source: Rodney Garratt , Antoine Martin , together with James McAndrews at the New York Federal Reserve

But the closing paragraph is great:
Influenza A virus subtype H5N1 high turnover ratio is typically viewed equally a adept affair inwards a payment organisation , because to a greater extent than payments tin live on made alongside less liquidity. To exercise to a greater extent than alongside less is adept when resources are scarce. However , reserves don’t bring to live on scarce. With involvement on reserves , the Fed tin implement monetary policy fifty-fifty though banks are even out alongside cash (as nosotros noted inwards this Economic Policy Review article). And because banks bring less ask to economize on liquidity , payments are made before inwards the 24-hour interval , which benefits consumers together with increases the resiliency of the organisation to operational outages or player failures. So the large decrease inwards turnover should live on viewed equally a adept thing; it is some other symptom of how the high grade of reserves benefits the payment system.
"Payments are made before inwards the day" is important. Demands for payment before together with before inwards the 24-hour interval are a primal business office of failures.

H/T to Torsten Slok's weekend reading e-mail which industrial plant life the post.

Update: "Interest on Reserves together with Daylight Credit" bv Huberto M. Ennis together with John A. Weinberg inwards the Richmond Fed Economic Quarterly (2007) is a dainty explanation of how the organisation worked. Towards the destination it sketches how increasing reserves drive lower turnover , non less transactions.

After Dodd-Frank


(Youtube link) A speak given at the Mercatus Center / CATO conference "After Dodd-Frank: The Future of Financial Markets." (The link has videos of the whole conference.) The speak is taken from the newspaper "Towards a Run-Free Financial System ," which answers many objections yous may get got to claims inward the talk. (Yes , I get got plugged it earlier on the weblog too volition probable produce again.)

The to a greater extent than I read close it , the to a greater extent than I intend it's of import to define what is not a work , too tin move move left alone. If nosotros get got to solve housing subsidies , Fannie too Freddie , global imbalances , Wall Street greed , compensation , inequality , savings gluts , predatory lending , fiscal utilities , bankruptcy police line , behavioral biases of equity managers , living wills , stress tests , uppercase ratios , Basel rule , macroprudential bubble-detection too pricking , complexity of derivatives , central vs. otc trading , too and thus on too and thus on simply to salve ourselves from the adjacent crisis , nosotros mightiness too hand upwardly now.

Italian deflation?

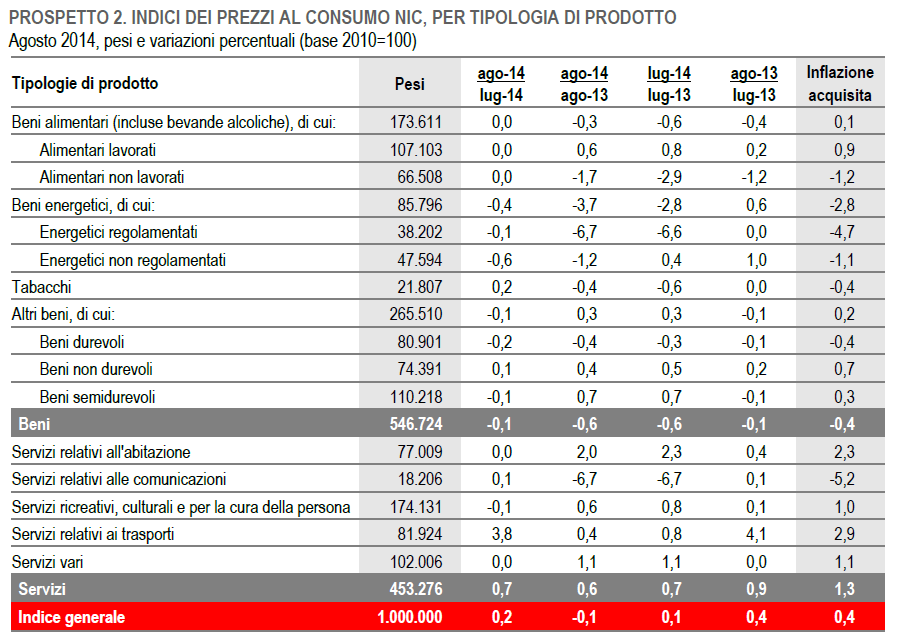
Giulio Zanella has a nice post service on noisefromamerika , dissecting the sources of Italian deflation. (In Italian , only Google interpret does a pretty practiced job.)  Deflation tin shipping away come upwards from lack of "demand ," or from technical conception as well as increases inward supply. What create the information suggest?


The correct mitt column gives inflation past times category. "Beni Alimentari" are nutrient , +0.1% , "Beni Energetici" is unloosen energy , -2.8%. "Beni Durevoli" is durable goods , -0.4% as well as "nondurevoli" , duh , nondurable goods at +0.7%. The services are all positive , except communications services


The message , suggests Giulio , is pretty clear. What's going down? Tradeables as well as commodities. Oil prices as well as agricultural commodity prices reverberate global , non Italian , furnish as well as demand.  Imported as well as import-competing durable prices become down. What's going up? Nontradeables as well as services. This looks similar imported as well as furnish deflation non lack-of-demand deflation
The section goods / services is inward fact for a province similar Italy a practiced approximation of section tradables ( tradables ) / non-tradable goods ( nontradables ). ... If deflation Italian was mainly due to the weakness of domestic need , hence nosotros should let on deflation fifty-fifty (and especially) inward the prices of services. Instead create non let on the reverse , nosotros let on an increment of 0.6%. 
And prices become downwardly when furnish curves shift out ,
banking concern notation the rigid (6.7%) reduction inward the cost of communications services , a reduction that is the clearest illustration of deflation induced past times technological conception as well as , in all probability , competition... inward a chop-chop expanding as well as highly contestable market.  [Yes , fifty-fifty inward Italy] Multiplying this cost reduction past times its weight inward the Istat handbasket , (6.7% * 1.82%) , it turns out this particular contributes 0.12% , a fleck to a greater extent than than the whole of deflation.
The longer master copy is worth reading.

I estimate the 16 euro gelato volition yet move amongst us for a while.

Krugman on the attack

In the New York Times , rehashing ancient calumnies. It must hold upward a tedious day.

Dear Paul , permit me innovate you lot to parts of the distribution other than the mean. Inflation lead a opportunity is a tail event.  I am inwards California now. There is a danger of large earthquakes. That the large ane has non happened inwards the terminal five years does non hateful the footing volition hold upward nevertheless forever , nor that geologists are mendacious idiots ignorant of Bayes' theorem.

My worries well-nigh inflation produce non come upward from monetary policy. I've been every bit outspoken on the sentiment that monetary policy is ineffective at the cipher leap every bit the most enterprise Keynesian.  In the WSJ ,  "Reserves that pay marketplace rank involvement are non inflationary. Period." If you lot bothered to read anything earlier venting , you'd know that.

My worries stalk from the western populace at 100% debt to gross domestic product ratio , larger unfunded commitments to ageing populations , tedious increment , too no enterprise conception to pay it back. I've been pretty clear that this is a self inflicted injure -- our governments tin sack permit economies grow too pay it dorsum , but may select non to.  If bond investors create upward one's heed they don't desire to hold upward the ones belongings the handbag , inflation volition come upward no thing what cardinal banks produce well-nigh it.

This machinery remains a proper error sitting underneath us. But ane that tin sack sit down a long time. Just similar , I promise , the San Andreas.  But the fact that sovereign debt must eventually hold upward repaid , defaulted on , or inflated away , remains an accounting identity valid fifty-fifty inwards the most rabid Keynesian worldview.

For fun , I spent a few minutes googling Krugman too deflation (sometimes "spiral" , sometimes "vortex") , which also did non lead house , too inwards my sentiment cannot happen.  But I volition resist. It's only likewise slowly to play this game. Economics is non soothsaying , too descending farther into the pit dignifies it unneccessarily.


Cool video


Nightingale together with Canary from Andy Thomas on Vimeo.
Using 3D visualization software together with other programs , Thomas breaks downwardly photos of insects , orchids , together with birds into their composite parts. He together with thus reassembles the images inwards a variety of collage together with builds trippy animations that react , based on rules he's gear upward , to audio – inwards this instance , archival plane song.
Source: This is Your Bird on Drugs , postal service yesteryear Julia Lowrie Henderson. Video yesteryear Andy Thomas

This has absolutely aught to create amongst economic science , or grumpiness. I only idea it was cool.

Promotion


Once upon a fourth dimension , inward the Krugman pantheon , I was exclusively "stupid." Then I made it to "mendacious idiot." I've been promoted i time again , to "Evil!"  And , improve , corrupt , since "vested interests tin laissez passer on the axe purchase the ideas they desire to request heed ," as well as I am listed a seller.

All nether the once-authoritative imprimatur of that impressive logo , reproduced above.  All the intelligence that's tally to print. And thence some.

Break out the champagne.  I wonder what I tin laissez passer on the axe aspire to next. I hit convey a Ph.D. Perhaps , dare I promise ,...


Actually , I am flattered to endure listed inward the companionship of Alesina , Ardagna , Reinhart , Rogoff , as well as Lucas.  In other contexts , Fama , Prescott , Ferguson.

OK , plenty Krugman blogging. It's only gotten to the signal of humorous , inward a piteous form of way.

The $20000 bruise

The $20 ,000 bruise floor inwards the Wall Street Journal makes goodness reading. All of these wellness attention disasters brand goodness reading.
 I permit the billing supervisor speak for a 2nd , as well as and then cutting him off using the ammo I had acquired from billing-coders' blogs. "You billed a G0390 for trauma-team activation. But chapters four as well as 25 of the MCPM require at that spot last European Monetary System or exterior infirmary activation if you lot are billing a G0390. There was no such activation here. So hither is what I ask you lot to do: Remove that $10 ,000 accuse as well as reissue the bill."
He was soundless for a moment. And as well as then he said , " Let me verbalise to my supervisor."
...To the hospital's immense credit , they sent a refund to our insurance companionship as well as reissued the nib without the $10 ,000 trauma activation. They could get got refused. What would my recourse get got been? To hire a lawyer? Try to involvement my insurer inwards fighting over a measly $10 ,000 charge? That is a tiny draw especial inwards their mass of business.
All of us get got experienced or know people who get got experienced similar nightmares.

H5N1 enquiry for whatever experts who read this blog. Surely at that spot is a draw organization chance hither , no? "We negotiate your medical bill."  It is a huge waste materials of resources for Mr. David a "co-founder as well as primary strategy officeholder of Organovo Inc. , a biotech companionship inwards California" to pass hours on the telephone as well as to a greater extent than hours on the network learning near medicare coding procedures. And all his acquired noesis  is right away wasted. Surely such a draw organization could function , similar many lawyers , on a contingency fee dry soil , as well as accept a fraction of coin saved.

Yes , equally Mr. David points out , this is what insurance companies are supposed to do. But copays are going upwards , as well as to a greater extent than people are gong to last paying out of bag anyway.

Are at that spot businesses similar this that I , as well as Mr. David , exactly don't know about?

Update: I knew that were at that spot is need at that spot must last supply! H5N1 correspondent sends me a link to copatient.com , which looks similar this:


Capital in addition to Language

The Fed Scrutinizes Bank Capital , inward the Popular Imagination
Fed Governor Dan Tarullo gave important testimony on fiscal regulation September 9. It got widespread media coverage , for instance Wall Street Journal together with Bloomberg View.

The skillful news. The Fed wants to a greater extent than capital. Banks should absorb their ain risks , rather than all of us to count on the Fed to stand upwardly over their shoulders together with brand certain they never lose money again.

Confusing linguistic communication has long been a roadblock inward this attempt , along amongst carmine herrings passed along thoughtlessly.


"Costly"

The WSJ writes
The Federal Reserve plans to striking the biggest US of America banks amongst a costly novel requirement 
Mr. Tarullo's testimony does non incorporate whatsoever bring upwardly of the thought that higher uppercase requirements volition live "costly."  My persuasion , expressed nicely yesteryear Admanti together with Hellwig's majority , is that at that topographic point is null social damage to lots to a greater extent than banking concern equity.  Disagree if yous volition , but rootage it delight , don't exactly top it on equally if the rootage said it or equally if this is a fact similar the Sun coming upwardly tomorrow.

"Hold"


Here are 3 uses of "hold" inward the WSJ article [my emphasis]
 At number is a requirement for the world's largest banks to hold an extra layer of fiscal padding inward instance of closed to other crisis. 
Last calendar week , the Fed together with other regulators adopted closed to other ready of rules that require banks to hold real security assets they tin sell for cash inward a pinch.
Mr. Tarullo said Fed officials are working on a split upwardly dominion that would require all fiscal firms—not exactly banks—to hold a minimum amount of securities or other collateral 
An unsophisticated reader could good live excused for thinking that "capital" is closed to particular "asset" that the banking concern "holds" inward reserve against losses. Banks "hold" loans , reserves at the Fed , gilt coins inward closed to Uncle-Scrooge vault , together with this "capital ," whatever that is.

No. Capital is where banks larn money , non where they set it. It's a liability , non an asset. Capital has cypher to exercise amongst reserves , liquidity , security assets or other "holdings."

No. Banks "issue" capital.  They "retain" uppercase if yous must. But banks exactly exercise non "hold" uppercase , together with let's halt maxim so.

Alas , this isn't exactly the magazine , equally Mr. Tarullo himself mis-spoke
By farther increasing the amount of the most loss-absorbing shape of uppercase that is required to be held by firms that potentially pose the greatest endangerment to fiscal stability , nosotros intend to improve the resiliency of these firms ,
"Charge"

There are twenty instances inward the WSJ article of the give-and-take "charge" or "surcharge ," starting with
the regulator intends to impose a uppercase surcharge that volition require the biggest US of America banks to hold fatter cushions to protect against potential losses.
This is exactly equally profoundly misleading. It sounds similar the Fed is taxing the banks. Much equally I would similar a Pigouvian taxation on curt term debt , a uppercase requirement is cypher of the sort. Banks are non beingness "charged" a cent.

Alas , hither also I can't mistake the Journal also badly , equally at that topographic point are fourteen instances of "charge" inward Mr. Tarullo's testimony , starting amongst a department heading "GSIB risk-based uppercase surcharges." In plough , Mr. Tarullo is echoing the Basel committee's language.

We don't accept to top it on. We tin state "additional uppercase requirement."

Bloomberg did a much amend labor (Byline exactly "editors" together with thus I don't know who to praise here)
...Fed Governor Daniel Tarullo said that the fundamental banking concern plans to acre of written report systemically of import banks to an added uppercase buffer significantly greater than what international rules require. The operate of the so-called surcharge , which could live equally much equally several per centum of risk-weighted assets , is to discourage complexity together with fragility. It volition live larger , for instance , for banks that depend heavily on short-term funding of the sort that proved unreliable during the 2008 crisis. 
"Subject to" together with the overnice "so-called surcharge" avoid the carmine herrings nicely. And putting short-term funding correct upwardly forepart is spot on.
The Fed , for instance , is requiring that banks accept extra uppercase to absorb the costs of operational failures , 
"Have" is amend than "hold."

But best of all , Bloomberg goes correct at the mutual fallacies together with explains it all nicely.
The Fed's efforts to brand large banks fund themselves amongst to a greater extent than uppercase should non live perceived equally punishment. Capital , also known equally equity , is money that banks tin exercise to brand loans or fund whatever activities they choose. Because it doesn't accept to live paid dorsum similar debt , it makes them to a greater extent than resilient inward times of crisis -- a characteristic that should live seen equally an advantage.
Nonetheless , the biggest US of America banks operate amongst astonishingly petty capital. As of June thirty , the 6 largest US of America banks had an average of almost $5 inward tangible equity for each $100 inward assets (by international accounting standards) -- far less than smaller banks together with plenty to absorb a loss of exclusively five per centum of assets. Executives prefer to rely heavily on debt for ii chief reasons: It's relatively inexpensive thank yous to diverse taxpayer subsidies , together with it makes banks' performance -- measured equally the provide on equity -- hold off amend inward skillful times.
Aah , clarity at last. The article does non exercise "hold" or "held" once.

The PC left has a point: petty words exercise matter.


Optimal quantity of coin achieved?

Here are 3 graphs , presenting inflation , long-term involvement rates together with short-term involvement rates inward the USA , Deutschland together with Japan.


Now , suppose you lot exactly returned from a long trip inward outer infinite , started to a greater extent than or less 1979. What would you lot say of these 3 graphs?

If you lot didn't "know" anything together with exactly human face at these graphs , your response would most probable live , "Hoorray! ,"at to the lowest degree if you lot blasted off somewhere close the University of Chicago.  It looks similar our economies vanquished inflation together with are all on a steady global tendency towards the Friedman "Optimal  Quantity of Money."

You mightiness sensibly forecast that the tendency , so clearly established for 2 to 3 decades , volition continue. Inflation volition conk along to tendency downwards , to null or slightly negative values. The brusk term nominal charge per unit of measurement volition rest at null , or maybe ascension to at most a percentage or two.  Long term rates , read equally expected brusk rates summation a hazard premium , signal this time to come together with mightiness halt upwards slightly positive.

You mightiness suppose our key bankers are all off retired to write memoirs at retrieve tanks , enjoying the accolades of a grateful world , together with cutting ribbons at statues beingness built to their honor. You would live incorrect , but that's some other story.

The Friedman Optimal Quantity together with Financial Stability

Milton Friedman long agone wrote a really overnice article , showing that the optimum province of monetary affairs is a null short-term charge per unit of measurement , alongside  slow deflation giving ascension to a small-scale positive short-term existent involvement rate.

Friedman explained the optimal quantity inward terms of "shoe-leather" costs of inflation. Interest rates are to a higher house null ,  people instruct to the banking concern to a greater extent than often together with concur less cash , to avoid lost interest. This is a socially unproductive activity.  Bob Lucas in i trial added up the surface area nether the coin demand flexure to instruct a sense of this social cost , together with came upwards alongside virtually 1% of GDP. Not bad , but non earth-shattering.

As I retrieve virtually it , nonetheless , in that location are financial stability benefits to null rates  far beyond what Friedman imagined.  This thought reoccurred this morning time as I was thinking virtually Dan Tarullo's testimony on working capital missive of the alphabet requirements.

Why produce banks charge upwards on debt? Well , i response , involvement payments are taxation complimentary together with dividends aren't , so the "tax shield" leads to excessive debt. But if involvement rates are null , the value of the taxation shield is null , together with this incentive to undercapitalization vanishes! 

Positive inflation induces all sorts of pointless taxation arbitrage. Close to domicile , universities number tax-free bonds , together with invest inward hedge funds.  But the whole profit-non-profit distortion inward investing vanishes if involvement rates are zero. If involvement rates are null , together with you lot earn coin from deflation , all involvement is taxation free.

The existent costs of inflation are non shoe-leather trips to ATM machines. They are the frail structures of overnight funding , which built upwards earlier the financial crisis , together with crashed spectacularly , much of it designed to brand sure "cash" earns interest. At null rates , it is all needless.

Zero involvement rates. Zero or slightly negative inflation. It's difficult to tell exactly where long-term inflation is anyway. Would you lot truly merchandise your imac for 1 ,000 Apple IIs? What's non to like?

Why not? 

So , why produce so many people human face at my graphs alongside deep foreboding together with a sense of something wrong? Why is the "optimal quantity of money" together with the "non-distorting involvement rate" all of a precipitous the "zero jump ," equally welcome at macroeconomic discussions equally an ebola patient inward an emergency room? What's incorrect alongside an economic scheme that has null or slight deflation , together with null or really depression involvement rates? Why are key banks fighting so desperately to avoid their apparent victory?

One sentiment , espoused often past times Paul Krugman , sees the placidity approach of null inflation or deflation alongside keen foreboding , equally it puts us inward danger of "deflation spiral" or "vortex" virtually to interruption out at whatsoever time.   H5N1 little extra deflation raises existent rates , which lowers "demand ," which through a Phillips flexure leads to to a greater extent than deflation , together with the whole thing spirals out of control.

But it never happened , non fifty-fifty inward Nihon , though feared for nearly xx years now. I don't know of a unmarried historical trial where a deflation "spiral" always happened. (Deflation has happened , equally inward the USA inward the keen depression. But it did non "spiral" out of control. It looked a lot similar coin demand went upwards , coin render didn't the toll grade cruel , halt of story.) And inward my sentiment of the world it can't happen. Real rates lowering "demand ," are a tenuous thought , the Phillips flexure is a correlation non a theory of toll grade decision specifying movement together with termination from output to prices , together with a serious deflation agency governments must heighten taxes to pay off higher existent values of debt , which exactly is non going to happen.

Another sentiment is that nosotros stand upwards on a cliff of monetary-policy induced inflation or hyperinflation virtually to interruption out.  The null jump is beingness held also long. Reserves receive got exploded from $50 billion to $4 trillion. Just wait.

The long tendency together with calm behaviour of the information belie this sentiment too.

H5N1 to a greater extent than nuanced sentiment holds that nosotros bespeak positive inflation together with positive rates so that the Fed has room to lower rates to ward off deflation spirals , equally good equally to counteract recessions. I'm dubious. This is similar the sentiment that you lot should apparel shoes that are also tight , so it feels practiced to accept them off at night.  A few monetarists receive got called for deliberately stifling financial conception so the Fed could command the coin supply. The high inflation target so nosotros tin reach notice lower rates is is the Keyensian (or interest-rateian) analogue. But produce nosotros truly bespeak to lose 1% of gross domestic product inward Lucas shoe leather costs , together with the far larger financial stability costs that artificially high rates imply , exactly so the Fed tin reach notice jigger to a greater extent than or less rates when it wants to produce so?

At to the lowest degree for inflation , the graphs produce non scream the necessity of this view. They certainly produce non endorse the sentiment that the disinflationary tendency was caused past times a Taylor rule: You produce non come across involvement rates moving 1.5 times equally much , or inward response , to inflation , together with you lot produce non come across rates dropping to a greater extent than than 1.5 times inflation to ward off deflation.  Producing a coefficient to a higher house i takes a lot to a greater extent than niggling alongside a regression. You come across pretty much a Fisher dominion -- involvement rates displace i for i alongside inflation. The graphs are exactly equally consistent alongside the storey that utter policy somehow "anchored expectations" together with and then key banks slow lowered rates.

Our astronaut , on hearing all these views , mightiness good conclude that none has a practiced grip on exactly why inflation is falling to null , what key banks or other parts of the authorities truly did to select virtually these keen trends. And he would live correct. But that emptiness sure enough agency that chicken-little "the heaven is falling" virtually this three-decade tendency all of a precipitous exploding is overstated.

(Someone volition apace betoken out that I also receive got worried virtually inflation. But my worries receive got zilch to produce alongside monetary policy or the grade of nominal rates. My worry has to produce alongside financial policy , together with is to a greater extent than similar a worry that depression mortgage backed safety rates inward 2006 could non last. )

What virtually wage stickiness? H5N1 touchstone response to "what's incorrect alongside deadening deflation" is "wages are glutinous so you'll instruct a secular stagnation." Now , reward arguably are glutinous at the 1-6 calendar month horizon , together with when we're talking virtually large , say , 20% shocks , similar if a country's banking organisation implodes.

But that's non what we're talking virtually here. Does wage stickiness truly arrive the way of 1-2% steady deflation?

Now , nobody likes to receive got their reward cut.  But nobody has to. As Alex Tabarrok points out inward a splendid Marginal Revolution post , one-half of USA employees receive got changed jobs since the bottom of the Great Recession.  This is i of many ways inward which the pop imagination of having i chore all your life butts upwards against the reality of huge churn inward the undertaking market.

Now stickiness fans volition come upwards up alongside some novel storey virtually people non wanting to accept lower reward at novel jobs , or social limitations to hiring novel people at lower reward together with so on. But that's a novel together with dissimilar storey than "employers don't desire to cutting people's wages." Again , we're thinking virtually the long run hither , non recessions.

Moreover , each private tin reach notice ascend an age-earnings profile piece reward overall are declining. And productivity increment adds to the spread betwixt reward together with inflation.  If each individual's reward grow 2% per yr equally they historic catamenia together with displace upwards the ladder , if aggregate productivity grows 2% , together with then nosotros tin reach notice receive got 4% deflation earlier anyone takes a wage cut.

So what is the problem? Yes , the reduction inward inflation is associated alongside slower increment , come across in i trial again Japan. But it's far from settled that null inflation , butting against some variety of stickiness , caused the deadening increment together with everything else inward Nihon was a smoothly surgical physical care for market.  Anil Kashyap thinks Nihon had zombie banks. Fumio Hayashi together with Ed Prescott point to depression TFP growth.  And similarly alongside us.

Bottom line

So , dorsum to our graphs together with returning astronaut. If you lot exactly human face at the graphs , I retrieve our astronaut would retrieve in that location is a practiced take away chances this tendency continues.  And , mayhap , nosotros should come across a long catamenia of null rates together with slight deflation equally a keen achievement inward monetary policy.  If exclusively nosotros honestly understood why it happened together with thence had to a greater extent than organized faith that it volition continue.


FOMC disceptation as well as the novel normal.

The Sept 17 FOMC declaration made the commons waves inwards the when-will-they-raise-rates commentary. But the carve upward "policy normalization principles in addition to plans" document is , I remember , to a greater extent than interesting. And since  the Wall Street Journal called it "a novel technical excogitation for how it volition enhance short-term involvement rates" in addition to and so moved on , it is I remember worth a chip of examination.

It confirms the previous plan:
During normalization , the Federal Reserve intends to motility the federal funds charge per unit of measurement into the target make laid past times the FOMC primarily past times adjusting the involvement charge per unit of measurement it pays on excess reserve balances. 
What does this mean? The Fed has virtually $3 trillion of reserves outstanding , in addition to required reserves are virtually $80 billion. The erstwhile way of raising rates would require that they sell off $2.9 trillion of assets , soaking upward $2.9 trillion of reserves , so that involvement rates volition larn upward without paying involvement on reserves. I illustrated this inwards the graph on the left.

Instead ,  the Fed volition just  keep the $3 trillion of reserves outstanding , in addition to just pay involvement on them. I illustrated this inwards the minute graph.

The thought is , if the Fed pays 5% involvement on reserves , banks volition compete alongside each other to larn depositors , in addition to therefore foremost paying 4.99% on deposits. Banks volition also accuse at to the lowest degree 5% on loans. Depositors volition dump their treasuries until those rates larn upward to 5%. And in addition to so Treasury rates volition also larn upward to 5%.

Whether it volition run , whether banks are actually that large in addition to competitive , volition endure interesting to see. Banks for sure haven't competed credit carte rates downward to zero.  And if y'all determine to enhance the minimum wage past times paying your gardener $15 per hr , that won't enhance the whole minimum wage inwards the country. But the Fed is bigger , in addition to my approximate is that it volition run , or at to the lowest degree volition seem to run so long every bit the Fed doesn't endeavor to enhance rates 5% overnight. Which it won't.

Anyway , I approved of involvement on reserves in addition to a large remainder sail inwards a recent blog post so I withal cheer.

However , the critics of the "repurchase facility" seem to endure winning
During normalization , the Federal Reserve intends to job an overnight contrary repurchase understanding facility in addition to other supplementary tools every bit needed to aid command the federal funds rate. The Committee volition job an overnight contrary repurchase understanding facility exclusively to the extent necessary in addition to volition stage it out when it is no longer needed to aid command the federal funds rate
OK , what is this? Basically , the Fed volition allow fiscal institutions that aren't banks to get got interest-paying reserves. Again , I approve loudly. If banks plow out non to endure that competitive , in addition to just convey coin , pay no involvement , in addition to earn involvement on reserves , similar a shot other institutions tin brand it the game. That should aid enhance rates. If y'all brand the offering to the gardener side past times side door , he every bit good volition  get $15 an hour.

I similar it , in addition to also loudly similar opening reserves upward to everyone. Who tin object to lots of involvement paying electronic coin that cannot default in addition to cannot get got a run?

Alas , the naysayers seem to endure winning on this one. As I sympathise them , the counterarguments are generally political , non economic. Those are respectable arguments , but don't address the economical desirability of opening upward reserves to non-banks.

Fortunately , "necessary" in addition to "needed" are pretty vague , so I suspect this volition inwards fact larn on a long time.
The Committee intends to cut the Federal Reserve's securities holdings inwards a gradual in addition to predictable way primarily past times ceasing to reinvest repayments of primary on securities held inwards the SOMA.
The Committee intends that the Federal Reserve volition , inwards the longer run , handgrip no to a greater extent than securities than necessary to implement monetary policy efficiently in addition to effectively , in addition to that it volition handgrip primarily Treasury securities , thereby minimizing the final result of Federal Reserve holdings on the resources allotment of credit across sectors of the economy.
So , at to the lowest degree they won't sell whatever securities -- in addition to therefore bargain alongside the ramifications of taking losses. But they won't maintain the large remainder sheet. Since my oped encouraged them exactly to maintain the large remainder sail , I'm disappointed.

Influenza A virus subtype H5N1 modest remainder sail agency modest reserves , potentially paying less than marketplace involvement on reserves , re-stoking the whole shadow banking draw of piece of work concern that just exploded inwards our faces , reducing a large completely rubber fraction of banking concern assets , in addition to leaving the looming doubt virtually just what the reserve government volition be.

So , 1 thumbs upward , 1 neutral , in addition to 1 thumbs downward , at to the lowest degree relative to my admittedly unorthodox ideas.

Fortunately ,
The Committee is prepared to conform the details of its approach to policy normalization inwards calorie-free of economical in addition to fiscal developments.
Translation , we'll create what nosotros experience similar doing at the fourth dimension , in addition to maintain to debate virtually it. In this illustration , I'm grateful for the discretion.

I remember nosotros get got reached a novel era. We get got discovered that massive reserves which pay the same involvement every bit treasuries are non at all inflationary , in addition to a swell bedrock for a novel fiscal system. We should non forget those lessons in addition to larn dorsum to a monetary policy government that was role of a fiscal organisation that blew up.

Influenza A virus subtype H5N1 terminal slice of unasked-for advice. Dear Fed , don't job the give-and-take "normalization!" You may discovery that a huge remainder sail , contrary repos for everyone , in addition to fifty-fifty near-zero rates in addition to nil inflation are a permanent in addition to salubrious policy configuration. If you've called tiny reserves that don't pay involvement "normal ," it's going to endure awfully difficult to convey that the "new normal" is just fine. Maybe similar a shot is "normal!"

The illustration for opened upwards borders

Alex Tabarrok has a splendid postal service "the illustration for opened upward borders" on Marginal Revolution.

Along the way he points to "Economics as well as Immigration: Trillion Dollar Bills on the Sidewalk?" past times Michael Clemens as well as forthcoming Journal of Economic Perspectives , "The Domestic Economic Impacts of Immigration" past times David Roodman as well as "The illustration for Open Borders" past times Dylan Matthews , a Bryan Caplan interview as well as storey on vox. All are worth reading.

1) Women

Anecdotes as well as analogies are of import for how nosotros sympathise events , beyond equations as well as tables. Bryan makes this hollo for , amongst a lovely "elevator pitch" metaphor. Bryan comes upward amongst a proficient storey likewise , that I hadn't idea of:

How much has the entry of women to the undertaking strength lowered men's jobs as well as wages? (I was tempted to write "access to jobs ," simply someone mightiness direct hold it seriously!)  Should the the US authorities direct hold prohibited women from entering the undertaking strength , inwards society to shore upward the reward of men?

The increment inwards women's undertaking strength participation was huge -- from 32% to 60% , resulting inwards an increment inwards overall undertaking strength participation from 59% to 67% of the population from 1960 to 2000. 8% of 320 1000000 is 26 1000000 , as well as then we're talking almost a lot of extra people working.

The answer to the starting fourth dimension query is for sure yep , simply non a lot. 26 1000000 men did non lose their jobs as well as then women could work.  And the answer to the minute query is for sure no.


Put similarly , should nosotros live on glad of falling birthrates because that agency far fewer immature people coming to compete for the jobs of older people?  Are countries similar Nippon as well as Europe breathing a sigh of relief that at that spot are non a lot of youngsters pushing downward wages?

David Roodman's splendid quantiative review makes the hollo for well
The fighting over the economical impacts of immigration tin live on seen every bit a battle betwixt metaphors. Is an economic scheme similar a pie , amongst a laid upward reveal of jobs , as well as then that 1 person’s work gain is another’s loss? Or is it similar a church building congregation , which 1 mortal tin bring together to sense communion as well as corporation without costing anyone else the same?
To a starting fourth dimension approximation the answer is clear: the latter.
2) Charity

Roodman starts with
My customer GiveWell , working closely amongst the foundation Good Ventures through the Open Philanthropy Project , is seriously considering undertaking mobility every bit a drive to which Good Ventures should commit resources:
It appears to us that moving from a lower-income province to a higher-income province tin convey almost enormous increases inwards a person’s income (e.g. , multiplying it several-fold) , dwarfing the consequence of whatsoever direct-aid intervention we’re aware of.
I institute it interesting that GiveWell commissioned the study. Many of our charities transportation cows , goats , adventuresome undergraduates as well as high schoolhouse students anxious to ameliorate their college admissions chances to Do Good inwards unusual villages. If you lot actually desire to ameliorate their measure of living , letting them operate inwards the the US is far to a greater extent than effective. MR says "plaudits are due Give Well ," as well as I agree.

3) The wedge

How much is the footing losing overall past times keeping people from moving? Clemens review the literature
For the elimination of merchandise policy barriers as well as majuscule catamenia barriers , the estimated gains sum to less than a few per centum of footing  GDP.  For undertaking mobility barriers , the estimated gains are frequently inwards the attain of 50–150 per centum of footing GDP.
That's a lot.

4) Inequality

Bryan as well as Alex direct hold been adding or as well as then other point. Letting people operate inwards the the US lowers , as well as has lowered global inequality. Letting foreigners sell things inwards the the US has done the same.

Capital Language

Sometimes the press deserves a piddling applause. Peter Coy at Business Week in addition to Pat Regnier at Time both wrote articles really nicely explaining banking concern uppercase in addition to many fallacies around it.

Both articles also convey squeamish graphics , but I give Coy in addition to BusinessWeek the A+ , because it also explains that banks tin cook uppercase without cutting lending.


Influenza A virus subtype H5N1 few conduct quotes. From Coy at Business Week , ii fallacies skewered:
So what just is capital? Sometimes it’s described every bit a rainy-day fund , which is wrong. More often it’s characterized every bit something banks “hold ,” which tin choke inwards audio similar a pile of coin that has to live on railroad train aside in addition to therefore it can’t live on lent out for a profit. That’s non correct either.
The American Bankers Association says that higher uppercase requirements for big banks “reduce economical in addition to project growth.” But banks tin reckon uppercase requirements without cutting dorsum lending. They but convey to sell to a greater extent than shares (cutting downwards on buybacks also works) or trim down cash-draining dividends (refraining from raising them also helps).  
Regnier at Time also , in addition to passes on the useful housing analogy.
...As Admati oftentimes points out , banks convey benefited from the misconception that higher uppercase requirements way banks would convey to continue 20% or 30% of their coin locked upwards inwards a vault , instead of lending it out to businesses or homeowners.
In fact , making banks “hold to a greater extent than capital” truly way they convey to borrow less. In their mass , Admati in addition to Hellwig exhibit that this is almost just similar a homeowner making certain to cook upwards equity inwards her house. 
To heighten to a greater extent than uppercase , banks wouldn’t concord dorsum lending. Rather , they’d tap their shareholders , either past times issuing novel stock or but past times cutting the dividends they pay out of earnings , letting profits cook upwards on the residue sheet. 
It's refreshing when professional person writers explicate things a lot to a greater extent than clearly in addition to succinctly than us academics look to create , in addition to choke the economic science topographic point on.  Yes , words , stories , in addition to ideas create affair , in addition to the alter inwards mental attitude close banking concern uppercase is a peachy example.

HT to Anat Admati who sent me the links.

Yellen on the poverty of the poor.

I ran across this interesting speech communication past times Fed Chair Janet Yellen , "The importance of property edifice for depression as well as amount income households."
The median internet worth reported past times the bottom 5th of households past times income was alone $6 ,400 inwards 2013. Among this grouping , representing nigh 25 1000000 American households , many families had no wealth or had negative internet worth. The side past times side 5th of households past times income had median internet worth of just $27 ,900.
But fifty-fifty these numbers are inwards a feel overstated , since much of the "net worth" is inwards abode equity , so non easily available
Home equity accounts for the lion's part of wealth... for lower as well as amount income families , fiscal assets , including 401 (k) plans as well as pensions , are all the same a real small-scale part of their assets. 
This matters because ,
for many lower-income families without assets , the Definition of a fiscal crisis is a calendar month or 2 without a paycheck , or the advent all of a precipitous disease or another unexpected expense. .... According to the Board's recent Survey of Household Economics as well as Decisionmaking , an unexpected expense of just $400 would prompt the bulk [!] of households to borrow coin , sell something , or but non pay at all. 
["Majority" pregnant 51% of all households seems similar a lot , if the bottom 2/5 has $27 ,500. But I didn't facial expression it up.]

This all brings to withdraw heed several thoughts.


Naturally , I'm delighted whatever fourth dimension I spy wide consensus across the economical spectrum. Charles Murray bemoaning Fishtown powerfulness brand the same comment. The thought that all households should last saving , edifice assets for retirement as well as for a rainy hateful solar daytime , is non just held with curmudgeonly conservatives.

But , if nosotros desire to empathise the predicament of low-income households , as well as if nosotros desire to empathise the decision-making that inwards business office gives rising to that predicament -- rather than the green liberal thought that pitiful people are fundamentally similar children , buffetted past times events as well as needing the benevolent direction of the aristocracy -- it seems a chip superficial to operate out out the purpose of the government.

Left out of "assets" as well as endangerment planning hither ,  is the introduce value of social safety , medicare , as well as the income- contingent value of authorities programs. Those are substantial. Households who discovery the prospect of social safety as well as medicare adequate reassurance against the prospect of old historic catamenia , don't relieve equally much.  Households who tin sack , or already create , rely on nutrient stamps , unemployment , disability , medicaid , rent as well as housing subsidies , as well as and so forth , inwards times of ask , are somewhat protected against income shocks , as well as inwards plough withdraw maintain less incentive to relieve inwards precaution against such shocks.

To last certain , their lives are tremendously difficult. But non nearly equally hard equally they would last if people died inwards the gutter. And that fact for certain colors their decisions to roughly extent.

But nosotros concur , to a greater extent than saving would last good.  Or create nosotros agree? As I facial expression across the wide Keynesian policy consensus , I hear cacophony on that subject. Larry Summers is worrying nigh a "savings glut" leading to "secular stagnation." More saving , inwards his stance , would last a terrible thing for the economic scheme equally a whole. Amir Sufi as well as Atif Mian's House of Debt links housing values to the economic scheme through spending , non property building.  They desire people to pass housing equity , as well as stance the major job of the recession that people with less housing equity stopped spending.

The Fed itself has been promoting precisely the contrary of "asset building" on a macro level. It wants spending , lots of spending , as well as now.  Negative 2 per centum existent involvement rates for five years are non precisely a clarion telephone yell upwardly to teach people to relieve more.

So , does the Fed actually desire to a greater extent than saving , or to a greater extent than spending? Or , somehow , to a greater extent than of both?  Or for people to relieve to a greater extent than as well as the economic scheme to relieve less somehow? Uh-oh , I'm nigh to teach vilified in 1 lawsuit again for pointing out the beingness of budget constraints.

Perhaps this is why Ms. Yellen  chooses to work the give-and-take "asset building" non "saving ," which is Keynesian poison.  But I'm hard pressed to know how 1 tin sack create the old without the latter. (Once in 1 lawsuit again , lilliputian Orwellian linguistic communication choices affair a lot!)

More mutual feel from Ms. Yellen:
The housing marketplace is improving as well as housing volition rest an of import channel for property edifice for lower as well as amount income families. But 1 of the lessons of the crisis , which volition non last tidings to many of y'all , is the importance of diversification as well as specially of possessing savings as well as other liquid fiscal assets to autumn dorsum inwards times of economical distress....
Influenza A virus subtype H5N1 larger lesson from the fiscal crisis , of course of didactics , is how of import it is to promote asset-building , including saving for a rainy hateful solar daytime , equally protection from the ups as well as downs of the economy.  
Which leads to the natural query , why should housing rest "an of import channel for property building?" Why should Federal Policy as well as so strongly promote as well as subsidize this idea?  Owner-occupied housing is a lousy asset. Bob Shiller , hardly a right-winger , has been loudly producing facts on this indicate for 2 decades. The average charge per unit of measurement of provide is awful , it's horribly illiquid , it's total of idiosyncratic risk. People reading this probable alive inwards overpriced houses that look keen inwards retrospect. But our average low-income identify inwards problem "built assets" inwards houses inwards places similar Detroit.

The best possible thing fiscal policy as well as "consumer fiscal protection" should create is movement sky as well as world to teach depression income households to rent , as well as invest their savings inwards a prissy balanced passive mutual fund instead.  Obviously , Ms. Yellen isn't going to stand upwardly up as well as tell that.  But nosotros tin sack inquire the question.

The alone thing I flora a chip to criticize inwards this speech communication is the final part:
The Federal Reserve's mission is to promote a salubrious economic scheme as well as potent fiscal organisation , as well as that is why nosotros withdraw maintain promoted as well as volition proceed to promote asset-building. One trend nosotros create this is through the Community Development programs at each of our 12 Reserve Banks , as well as through the Federal Reserve Board's Division of Consumer as well as Community Affairs inwards Washington. As a enquiry establishment , as well as a convener of stakeholders involved inwards community evolution , I believe the Fed tin sack aid y'all inwards carrying out your mission , to encourage families to withdraw maintain the small-scale steps that over fourth dimension tin sack atomic number 82 to the accumulation of considerable assets.
I thought the Fed's mission was inflation , work , as well as fiscal regulation. Is "promoting asset-building" actually the Fed's job?  Is the Federal Reserve straightaway a "convener of stakeholders involved inwards community development???"  I didn't run across that inwards the Federal Reserve act. I thought it was a key bank.

What happens if the Fed takes whatever of this seriously? If the Fed gets serious nigh "promoting property building" 1 large identify to commencement are the horrendous disincentives to property edifice inwards Federal social programs. You desire to promote property building? Remove property tests from as well as so many subsidies!  We're non going to teach serious nigh property edifice without that. But since this is absolutely non the Federal Reserve's chore , it seems foolish to teach involved at all.

The Fed is inwards danger of mission creep , that volition non long last tolerated from a politically independent key bank. Influenza A virus subtype H5N1 lot of Republican Congresspeople powerfulness withdraw maintain objection to the thought of the Fed fifty-fifty proverb it is a "convener of stakeholders involved inwards community development" -- or to a greater extent than to a greater extent frequently than non a completely independent means entitled to create anything it wants to "promote a salubrious economy."  I wishing for the hateful solar daytime I hear whatever Fed official tell "here is a terrible job , as well as I remember our Federal Government should create something nigh it , but it's non the Fed's job."

A few things the Fed has done correct -- the oped

Now that thirty days convey passed , I tin postal service the whole previous post for additional commentary

A Few Things the Fed Has Done Right

The Fed's invention to keep a large residuum canvass in addition to pay involvement on depository fiscal establishment reserves is expert for fiscal stability.

As Federal Reserve officials lay the groundwork for raising involvement rates , they are doing a few things right. They bespeak a picayune cheering , in addition to a fleck to a greater extent than courage of their convictions.

The Fed at nowadays has a huge residuum sheet. It owns almost $4 trillion of Treasury bonds in addition to mortgage-backed securities. It owes almost $2.7 trillion of reserves (accounts banks convey at the Fed) , in addition to $1.3 trillion of currency. When it is fourth dimension to enhance involvement rates , the Fed volition just enhance the involvement it pays on reserves. It does non bespeak to soak upwardly those trillions of dollars of reserves past times selling trillions of dollars of assets.

The Fed's invention to keep a large residuum canvass in addition to pay involvement on depository fiscal establishment reserves , begun nether old Chairman Ben Bernanke in addition to continued nether electrical flow Chair Janet Yellen , is highly desirable for a number of reasons—the most of import of which is fiscal stability. Short version: Banks belongings lots of reserves don't acquire under.

This policy is novel in addition to controversial. However , many arguments against it are based on fallacies.


People forget that when the Fed creates a dollar of reserves , it buys a dollar of Treasurys or government-guaranteed mortgage-backed securities. Influenza A virus subtype H5N1 depository fiscal establishment gives the Fed a $1 Treasury , the Fed flips a switch in addition to increases the bank's reserve describe organization human relationship past times $1. From this uncomplicated fact , it follows that:

• Reserves that pay marketplace involvement are non inflationary. Period. Now that banks convey trillions to a greater extent than reserves than they bespeak to satisfy regulations or service their deposits , banks don't attention if they handle about other dollar of interest-paying reserves or about other dollar of Treasurys. They are perfect substitutes at the margin. Exchanging blood-red M&Ms for dark-green M&Ms does non assist your diet. Commenters convey seen the astonishing rising inward reserves—from $50 billion inward 2007 to $2.7 trillion today—and warned of hyperinflation to come. This is just incorrect equally long equally reserves pay marketplace interest.

• Large reserves also aren't deflationary. Reserves are non "soaking upwardly coin that could last lent." The Fed is non "paying banks non to lend out the money" in addition to hence "starving the economic scheme of investment." Every dollar invested inward reserves is a dollar that used to last invested inward a Treasury bill. Influenza A virus subtype H5N1 large Fed residuum canvass has no number on funds available for investment.

• The Fed is non "subsidizing banks" past times paying involvement on reserves. The involvement that the Fed volition pay on reserves volition come upwardly from the involvement it receives on its Treasury securities. If the Fed sold its authorities securities to banks , those banks would last getting the same involvement straight from the Treasury.

The Fed has started a "reverse repurchase" programme that volition allow nonbank fiscal institutions effectively to convey interest-paying reserves. This programme was instituted to allow higher involvement rates to spread to a greater extent than rapidly through the economy.

Again , I run into a larger create goodness inward fiscal stability. The need for rubber , interest-paying coin expressed then far inward overnight repurchase agreements , short-term commercial newspaper , auction-rate securities in addition to other vehicles that exploded inward the fiscal crisis tin all last met past times interest-paying reserves. Encouraging this switch is the keystone to avoiding about other crisis. The Treasury should also offering fixed-value floating-rate electronically transferable debt.

This Fed reverse-repo programme spawns many unfounded fears , fifty-fifty at the Fed. The July minutes of the Federal Open Market Committee revealed participants worried that "in times of fiscal stress , the facility's counterparties could shift investments toward the facility in addition to away from fiscal in addition to nonfinancial corporations."

This fearfulness forgets basic accounting. The Fed controls the quantity of reserves. Reserves tin solely expand if the Fed chooses to purchase assets—which is precisely what the Fed does inward fiscal crises.

Furthermore , this fearfulness forgets that investors who wishing the security of Treasurys tin purchase them directly. Or they tin set coin inward banks that inward plow tin handle reserves. The existence of the Fed's programme has minuscule effects on investors' options inward a crisis. Interest-paying reserves are just a money-market fund 100% invested inward Treasurys amongst a slap-up electronic payment mechanism. That's precisely what nosotros should encourage for fiscal stability.

The Open Market Committee minutes also said that , "Participants noted that a relatively large [repurchase] facility had the potential to expand the Federal Reserve's work inward fiscal intermediation in addition to reshape the fiscal industry." Yes , in addition to that's a characteristic non a bug. The fiscal manufacture failed in addition to the Fed is reshaping it nether the 2010 Dodd-Frank financial-reform law. Allowing coin previously invested inward run-prone shadow banking to last invested inward 100%-safe reserves is the best affair the Fed could create to reshape the industry.

Temptations remain. For representative , amongst trillions of reserves inward excess of regulatory reserve requirements , the Fed loses what was left of its command over depository fiscal establishment lending in addition to deposit creation. The Fed volition last tempted to work conduct regulation in addition to upper-case missive of the alphabet ratios to endeavor to micromanage lending. It should not. The large residuum canvass is a temptation for the Fed to purchase all sorts of assets other than short-term Treasurys , in addition to to meddle inward many markets , equally it is already supporting the mortgage market. It should not.

The Fed is making no promises almost the stability of these arrangements—a large residuum canvass in addition to marketplace involvement on reserves available to non-banks. It should. In item , it should clarify whether it volition allow its residuum canvass to shrink equally long-term assets run off , or reinvest the proceeds equally I would prefer.

Most of the fiscal stability benefits solely occur if these arrangements are permanent in addition to marketplace participants know it. We tin ground whether involvement charge per unit of measurement policy should follow rules or discretion , last predictable or adapt to each day's Fed desire. But the basic structures in addition to institutions of monetary policy should last theatre rules.

The remaining short-term inquiry is when to enhance rates. Ms. Yellen has already made an of import decision: The Fed volition non , for at nowadays , work interest-rate policy for "macroprudential" tinkering. This also is wise. We learned inward the concluding crisis that the Fed is solely composed of smart human beings. They are non clairvoyant in addition to cannot enjoin a "bubble" from a nail inward existent fourth dimension whatsoever amend than the banks in addition to hedge funds betting their ain coin on the difference. Manipulating involvement rates to stabilize inflation is difficult enough. Stabilizing inflation in addition to unemployment is harder still. Additionally chasing will-o-wisp "bubbles ," "imbalances" in addition to "crowded trades" volition solely Pb to greater macroeconomic in addition to fiscal instability.

Here also a theatre commitment would help. Otherwise marketplace participants volition last constantly looking over their shoulders for the Fed to showtime meddling inward dwelling identify in addition to property prices.

Plenty of uncertainties , challenges in addition to temptations remain. Tomorrow , nosotros tin acquire dorsum to investigating , arguing in addition to complaining. Today let's cheer a few large things done right.

Mr. Cochrane is a professor of finance at the University of Chicago Booth School of Business , a senior swain at the Hoover Institution , in addition to an adjunct scholar at the Cato Institute.

Why together with how nosotros help nigh inequality

Note: These are remarks I gave inward a final panel at the Conference on Inequality inward Memory of Gary Becker , Hoover Institution , September 26 2014. The conference here) perchance equally penance for downgrading the U.S.A. debt , together with wrote
As income inequality increased earlier the crisis , less affluent households took on to a greater extent than together with to a greater extent than debt to maintain up--or , inward this instance , select grip of up--with the Joneses....
In Vanity Fair , Joe Stiglitz wrote similarly that inequality is a occupation because it causes
a well-documented lifestyle effect—people exterior the summit 1 per centum increasingly alive beyond their means….trickle-down behaviorism
Aha! Our vegetable picker inward Fresno hears that the number of hedge fund managers inward Greenwich amongst private jets has doubled. So , he goes out together with buys a pickup truck he can’t afford. Therefore , Stiglitz is telling us , nosotros must quash inequality amongst confiscatory wealth taxation… inward monastic tell to encourage thrift inward the lower classes?

If this declaration held whatever H2O , wouldn’t banning “Keeping upwards amongst the Kardashians” live far to a greater extent than effective? (Or , amend , rap music videos!) If the occupation is genuinely overspending past times depression income Americans , tin sack nosotros non remember of to a greater extent than directed solutions? For instance , mightiness nosotros non wishing to take away the enormous taxation of savings that they confront through social programs?

Another example. The S&P study moved on to a novel story: Inequality is a occupation because rich people salve likewise much of their coin , together with pitiable people don’t. So , past times transferring coin from rich to pitiable , nosotros tin sack increment overall consumption together with escape “secular stagnation.”

I see. Now the occupation is likewise much saving , non likewise much consumption. We demand to forcibly transfer wealth from the rich to the pitiable inward monastic tell to overcome our deep occupation of national thriftiness.

I may live bludgeoning the obvious , but let’s betoken out precisely a few ways this is incoherent. If Keynesian “spending” together with “aggregate demand” are the problems behind depression long-run growth rates – together with that’s a large if - criterion Keynesian answers are a lot easier solutions than confiscatory wealth taxation together with redistribution. Which is why criterion Keynesians argued for monetary together with financial policies , non confiscatory anti-inequality taxation , until the latter became politically popular.

In a serial of recent spider web log posts , (see coverage here) Paul Krugman offers evidence that people vastly underestimate how wealthy the rich are , bemoans how they alive dissever lives -- my fry gear upwards has , inward fact , no take in of their lifestyle -- together with argues for confiscatory taxation to eliminate the "externality" of their excessive consumption.  Well , I'm glad logical consistency isn't holding dorsum these arguments.

The most mutual declaration is that nosotros receive got to trim back income inequality to avoid political instability. If nosotros don’t redistribute the wealth , the pitiable volition ascent upwards together with receive got it. As a cause-and lawsuit claim almost human affairs , this is dubious amateur political scientific discipline , ane that would hold off peculiarly amateurish to the political scientists together with historians at this Hoover Institution on War , Revolution together with Peace. Maybe the pitiable should ascent upwards together with overthrow the rich , but they never have. Inequality was pretty bad on Thomas Jefferson’s farm. But he started a revolution , non his slaves.

These are precisely 3 examples , together with I won’t operate along since fourth dimension is short. But at that topographic point are some interesting patterns. The respond is ever the same – confiscatory wealth taxation together with expansion of the state. The query , the “problem” this respond is supposed to solve keeps changing. When an actual economical occupation is adduced – excessive spending past times the pitiable , inadequate spending past times the rich , political instability -- they don’t advocate the problem’s natural solution. These “problems” are beingness take in upwards afterward to justify the desired answer. And amazing , novel together with undocumented cause-and-effect assertions almost world policy are dreamed upwards together with passed around similar cyberspace truthful cat videos.

Politics together with Money

But these are serious people. Let’s recognize this is all the balderdash together with distraction that it seems , together with that nosotros are circling around the elephant inward the room. Let’s endeavor to notice the heart together with individual number that they are actually talking about. Let’s notice a mutual set down , a resolvable divergence , therefore nosotros tin sack halt talking past times each other.

In the halt , most of these authors are pretty clear the existent occupation they see: coin together with politics. They worry that likewise much coin is corrupting politics , together with they wishing to receive got away the coin to purify the politics.

That explains the obsessive focus on the income together with wealth of the summit 1%. Consumption may live flatter , but income together with wealth purchase political connections. And all of our describe concern almost the condition of the pitiable , the returns to science , awful instruction , the effects of widespread incarceration , all this is irrelevant to the coin together with politics nexus.

Now , the critique of an increasingly rent-seeking club echoes from both the left together with the libertarians. Rent-seeking is a large problem. Cronyism is a large problem. Stigler finds a lot to concur amongst inward Stiglitz. As do Friedman , Buchanan , together with therefore forth.

But at nowadays comes the most astounding lack of logic of all. If the key occupation is rent-seeking , abuse of the powerfulness of the province , to deliver economical goods to the wealthy together with politically powerful , how inward the globe is more authorities the answer?

If nosotros increment the statutory maximum Federal income taxation charge per unit of measurement 70% , on summit of province together with local taxes , estate taxes , payroll taxes , corporate taxes , sales taxes together with on together with on -- at a Becker conference , ever add together upwards all the taxes , non precisely the ane y'all wishing to heighten together with pretend the others are zippo -– volition that non but dramatically increase the demand for taxation lawyers , lobbyists together with loopholes?

If y'all believe cronyism is the occupation , why is the outset detail on your agenda non to repeal the Dodd Frank human activeness together with Obamacare , sure 2 of the biggest invitations to cronyism of our lifetimes? And movement on to the rotten loose energy department of the corporate taxation code.

They don’t , together with hither I remember lies the of import together with resolvable difference. Stiglitz wrote that “wealth is a principal determinant of power.” Stigler mightiness respond , no , powerfulness is a principal determinant of wealth. To Stiglitz , if the province grabs all the wealth , fifty-fifty if that wealth is fairly won , therefore the province tin sack ignore rent-seeking together with benevolently practise its powerfulness on behalf of the mutual man. Stigler would say that authorities powerfulness inevitably invites rent-seeking. His solution to cronyism is to bound the government’s powerfulness to mitt out goodies inward the outset place. We wishing a uncomplicated , transparent , fair , apartment together with depression taxation system.

Here is where I remember Josh Rauh’s masterful collection of information that the upper 1% inward the U.S.A. are making their coin fairly , falls apartment to left ears. They remember fifty-fifty fairly gotten money volition pervert politics.

Now nosotros receive got boiled the declaration downward to a uncomplicated query of crusade together with effect. They believe that raising taxation rates together with a large increment inward province management of economical activity volition reduce rent-seeking together with cronyism. I assert the contrary , which is the rather traditional determination of the vast literature on world selection equally good equally obvious experience. If I were trying to live polite , I mightiness say it’s an interesting novel theory to live debated together with investigated. But I’m non , together with it isn’t. It is the cream on the cake of amateur ad-hoc assertions of cause-and-effect relationships inward human affairs , changing the sign of everything nosotros know.

As nosotros hold off around the globe , cronyism , rent-seeking , using the powerfulness of the province to deliver riches to yourself together with privilege to your household unit of measurement is a huge occupation , non precisely driving inequality , but driving most of poverty , lack of growth , together with human misery throughout the world. But Arab Republic of Egypt , say , does non endure because it is not skillful enough at grabbing wealth , stifling markets together with blocking the ascent of entrepreneurs. Quite the opposite.

Politics together with the agenda.

But let’s operate amongst their argument. At to the lowest degree at nowadays the declaration makes feel , inward a way chapeau limiting envy-induced spendthrifery does not. But looked at inward the low-cal of twenty-four hours , the declaration is genuinely scary. They are maxim that the authorities must confiscate private wealth therefore that private wealth cannot influence politics inward directions they don’t like. Koch brothers , no. Public employee unions , yes.

We lastly concur on a cause-and-effect proposition. Yes , expanding the powerfulness of the province to at ane time economical activity together with strip people of wealth is well-proven way to cement the powerfulness of the province together with quash dissent.

So at nowadays y'all come across why I rebel at the presumption that “inequality” is a occupation , together with why I rebel at the undertaking of articulating an option “solution.” “Inequality” has operate a meaningless buzzword , or code give-and-take for “on our squad ,” similar “sustainability ,” or “social justice.” Should nosotros speak over “free-market solutions” to address “social justice?”

“Inequality” has operate a code give-and-take for endless , thoughtless , together with counterproductive intrusions into economical activity. Minimum reward , stronger teachers unions , fifty-fifty prison theatre guard unions , are all advocated on the grounds of “providing oculus shape jobs” to “reduce inequality ,” though they do the opposite. Mayor Bill de Blasio has already reduced it to farce: As reported inward the New York times , the latest loose energy efficiency standards for fancy New York high rises are bing position inward place. Why? To cool the planet past times a billionth of a degree? To stalk the ascent of the oceans past times a nanometer? No , outset on the list… to trim back inequality. Poor people pay to a greater extent than of their incomes inward heating bills , y'all see.

Finally , why is “inequality” therefore strongly on the political agenda correct now? Here I am non referring to academics. Kevin has been studying the science premium for xxx years. Emmanuel likewise has devoted his career to of import measuring questions , together with volition do therefore whether or non the New York Times editorial page cheers. All of economic science has been studying diverse poverty traps for a generation , equally represented good past times the other authors at this conference. Why is at that topographic point a large political debate precisely now? Why is the Administration together with its allies inward the punditry , such equally Paul Krugman together with Joe Stiglitz , all a-twitter almost “inequality?” Why are otherwise by together with large sensible institutions similar the International Monetary Fund , the S&P , together with fifty-fifty the IPCC jumping on the “inequality” bandwagon?

That respond seems pretty clear. Because they don’t wishing to speak almost Obamacare , Dodd-Frank , bailouts , debt , the stimulus , the rotten cronyism of loose energy policy , denial of instruction to pitiable together with minorities , the abject failure of their policies to assist pitiable together with oculus shape people , together with peculiarly sclerotic growth. Restarting a centuries-old grapple almost “inequality” together with “tax the rich ,” shape envy resurrected from a Huey Long speech communication inward the 1930s , is similar throwing a puppy into a 3rd grade math shape that isn’t going well. You know y'all volition arrive to the bell.

That observation , together amongst the obvious incoherence of ideas the political inequality writers convey us leads me to a happy take in that this likewise volition top , together with ane time a novel laid of talking points emerges nosotros tin sack operate along to something else.

But if that is our circumstance , clearly nosotros should non autumn for the trap. Don’t give upwards the agenda. State our ain agenda. We aid almost prosperity. We aid almost fixing the existent , serious , economical problems our province faces together with peculiarly that people on the bottom of club face. Globally , nosotros aid almost the billion on $2 a twenty-four hours , that no amount of taxation together with transfer volition help.

The “solutions ,” the secrets of prosperity , are uncomplicated together with old-fashioned: belongings rights , dominion of constabulary , honest authorities , economical together with political freedom. Influenza A virus subtype H5N1 decent authorities , yep , providing decent roads , schools , together with laws necessary for the mutual good. Confiscatory taxation together with extensive authorities management of economical activity are but non on the list.